Aleksandr Blogerman / New ventures
I’ve got an idea. Where would you start?
I’d start with the first customer. What can we offer them? What would they pay for? And what do we need to build from scratch to deliver on that promise?
Maybe you already have a business, customers, infrastructure and a team. Or maybe it’s just you and an idea you can’t get out of your head.
Together, we’ll figure out what to launch first. I’ll work out how much time and money it’ll take. We’ll weigh how much of your own money to put in and whether it makes sense to bring in outside funding. If you decide to go ahead, I can lead the launch, from putting the team together to making the first sales.
Launch, business case or partnership — three ways to start.
Where you might be now
You already have customers and resources. Which new direction fits?
I compare options on demand, economics and what you can actually deliver, and pin down what to test before you invest.
You have a specific idea. Is it worth the investment?
I build the business case: financing needs, scenarios and the material you need to present to shareholders, the board or investors.
You’ve decided to launch. Who will run it?
I define the MVP, put together the team and vendors, coordinate business, technology and marketing, and take responsibility for budget, timing and delivery.
Your product works but needs to grow.
Pricing, monetisation, conversion, retention and cross-selling. Where growth is held back by the organisation, I sort out process ownership and what to automate.
Each one ends with a decision and a plan you can act on.
Selected recent projects
10 projects · Company names withheld under NDA
- 01
Short-form drama platform
USA
My role: Built the financial model and worked with the team on product development, launch and production in the US.
Outcome or scale: $4m total investment, including about $1m in paid user acquisition · 15 original in-house productions
- 02
Self-storage access software
Spain
My role: From Excel and phone calls to app-managed access: development, implementation, troubleshooting, digitisation and cross-selling.
Outcome or scale: Operator is a local market leader with 70+ locations; the software was then sold to other operators by subscription
- 03
Streaming service
Azerbaijan
My role: Launched and developed an OTT service with the team.
Outcome or scale: About 65,000 users when my involvement ended
- 04
Fintech and super-app
Azerbaijan and Ukraine
My role: Credit, loyalty and digital services; took part in securing partner funding.
Outcome or scale: Company portfolio over $150m
- 05
Retail services
Ukraine, Kazakhstan, Azerbaijan and Georgia
My role: I grew service sales and improved the customer experience across the retail network. My last role was Chief Innovation Officer in Azerbaijan. I digitized and automated around 100 processes, introduced NPS and worked on CRM and ERP systems.
Outcome or scale: Service sales doubled. Together, the business units I oversaw generated more than $35 million in annual profit.
- 06
Electric scooter sharing
Azerbaijan
My role: With the team, piloted 60 scooters, verified the economics and scaled up.
Outcome or scale: 60 → 260 scooters · 20,000+ users · paid back in two years
- 07
A platform for filmmakers and festivals
England
My role: My team and I designed how filmmakers submit entries, juries select films and festivals put together their screening programmes.
Outcome or scale: Filmmakers can submit festival entries through the platform.
- 08
Server infrastructure
Slovakia
My role: Worked on raising capital for GPU compute infrastructure. The investment case connected customer demand with power availability, equipment procurement and the commissioning schedule.
Outcome or scale: Investment preparation
- 09
Domain registry venture
Australia
My role: I prepared the project to raise capital from investment funds. The team has applied to ICANN to operate two new domain extensions, one for content creators and one for the gaming industry.
Outcome or scale: $10m fundraising target: $5m per extension for potential auctions. The applications are pending.
- 10
Industrial tooling
Ukraine
My role: I prepared and defended the investment case for mould manufacturing, then coordinated equipment procurement, site reconstruction and the search for customers in India and Pakistan.
Outcome or scale: Investment case of roughly $1.5m
Should a marketplace launch its own bank?
- Q1How much funding will it take?
- Q2When will the bank break even?
- Q3What if fewer customers use their cards?
A marketplace was considering a neobank of its own. I worked with the project team to model how customers would start using it, where the income would come from and how much funding it would need.
Synthetic assumptions that show the method. Not the client’s numbers, not a forecast, and not a report of results — the project was a business case.
Share of issued cards that customers actually start using. Move it to see how the answers change.
Deepest cumulative cash deficit before any investment, reached in month 37.
How much funding will it take?
First month after which the monthly operating result stays at or above zero for the rest of the five years.
When will the bank break even?
Month when cash returned to the investor equals cash put in, under the rules below.
What if fewer customers use their cards?
The investor needs to be ready to put in around €7.0m before the bank funds itself in month 37. It covers its monthly costs from month 27, and returns the investment in month 56. Worth taking to the board, with activation as the number to watch.
Two charts with a shared month axis from 1 to 60. The full numbers are in the five-year breakdown below.
Assumptions and formulas
- Card activation
- 60%
- Acquisition cost
- €25 per issued card
- Credit losses
- 4% a year
- Applications
- ramp to 30,000 a month over 12 months
- Card issued
- 70% of applications
- Credit card share
- 30% of active customers
- Monthly churn
- 1.5% of active cards
- Card spend
- €320 per active card a month, 0.9% fee income
- Lending
- €140 new borrowing per credit card a month, 12% of balance repaid monthly, 20% annual rate
- Deposits
- €300 per active customer, 1.5% annual rate
- Team
- €450,000 a month
- Card operations
- €1.20 per active card a month
- Software capex
- €700,000 a month for 6 months, then €40,000
- Liquidity buffer
- €1,000,000 kept in cash at all times
- Operating result = card fees + interest − deposit interest − credit losses − acquisition − team − card operations.
- Loan balance = opening balance + new loans − repayments − write-offs.
- Cash flow before financing = operating result + write-offs (non-cash) − capex − new loans + repayments + change in deposits. Losses are counted once.
- Peak outside funding = the lowest point of cumulative cash flow before financing.
- Investor rules: the investor tops cash up to the buffer whenever it falls below. Cash is returned only when it exceeds the buffer plus every future funding need, and never more than undistributed operating profit.
- Payback = first month cumulative returns reach cumulative contributions. Not reached in 60 months = beyond five years.
Five-year breakdown
| Y1 | Y2 | Y3 | Y4 | Y5 | |
|---|---|---|---|---|---|
| Active cards, year end | 77,560 | 204,024 | 309,512 | 397,503 | 470,899 |
| Card fee income | €1.06m | €5.11m | €9.08m | €12.39m | €15.15m |
| Interest income | €565k | €5.30m | €12.81m | €19.95m | €26.08m |
| Deposit interest | −€109k | −€618k | −€1.14m | −€1.58m | −€1.95m |
| Credit losses | −€113k | −€1.06m | −€2.56m | −€3.99m | −€5.22m |
| Acquisition | −€3.41m | −€6.30m | −€6.30m | −€6.30m | −€6.30m |
| Team | −€5.40m | −€5.40m | −€5.40m | −€5.40m | −€5.40m |
| Card operations | −€440k | −€2.13m | −€3.78m | −€5.16m | −€6.31m |
| Operating result | −€7.85m | −€5.09m | €2.70m | €9.91m | €16.06m |
| Software capex | −€4.44m | −€480k | −€480k | −€480k | −€480k |
| New loans | −€15.41m | −€74.57m | −€132.42m | −€180.68m | −€220.93m |
| Principal repaid | €4.07m | €38.18m | €92.25m | €143.64m | €187.80m |
| Change in deposits | €23.27m | €37.94m | €31.65m | €26.40m | €22.02m |
| Cash flow before financing | −€249k | −€2.96m | −€3.74m | €2.77m | €9.68m |
| Investor contributions | €4.33m | €0 | €3.62m | €41k | €0 |
| Returns to investor | €0 | €0 | €0 | €0 | −€8.00m |
| Loan book, year end | €11.23m | €46.55m | €84.17m | €117.22m | €145.13m |
| Deposits, year end | €23.27m | €61.21m | €92.85m | €119.25m | €141.27m |
| Cash, year end | €4.08m | €1.12m | €1.00m | €3.81m | €5.50m |
Reconciliations
- Cumulative operating result
- €15.72m
- − Cumulative capex
- −€6.36m
- − Loan book at month 60
- −€145.13m
- + Deposits at month 60
- €141.27m
- = Cumulative cash flow before financing
- €5.50m
- + Contributions − returns
- €0
- = Cash at month 60
- €5.50m
✓ Both totals match the monthly series.
Ways to work together
- ALead the launch
- We agree the scope and my decision rights. I build the team and deliver the launch.
- BBuild the business case
- The idea, the options, the economics, the funding and the risks — and the material you need to decide.
- CWork as partners
- For selected opportunities with shared upside. We agree accountability and terms at the outset.
Aleksandr Blogerman
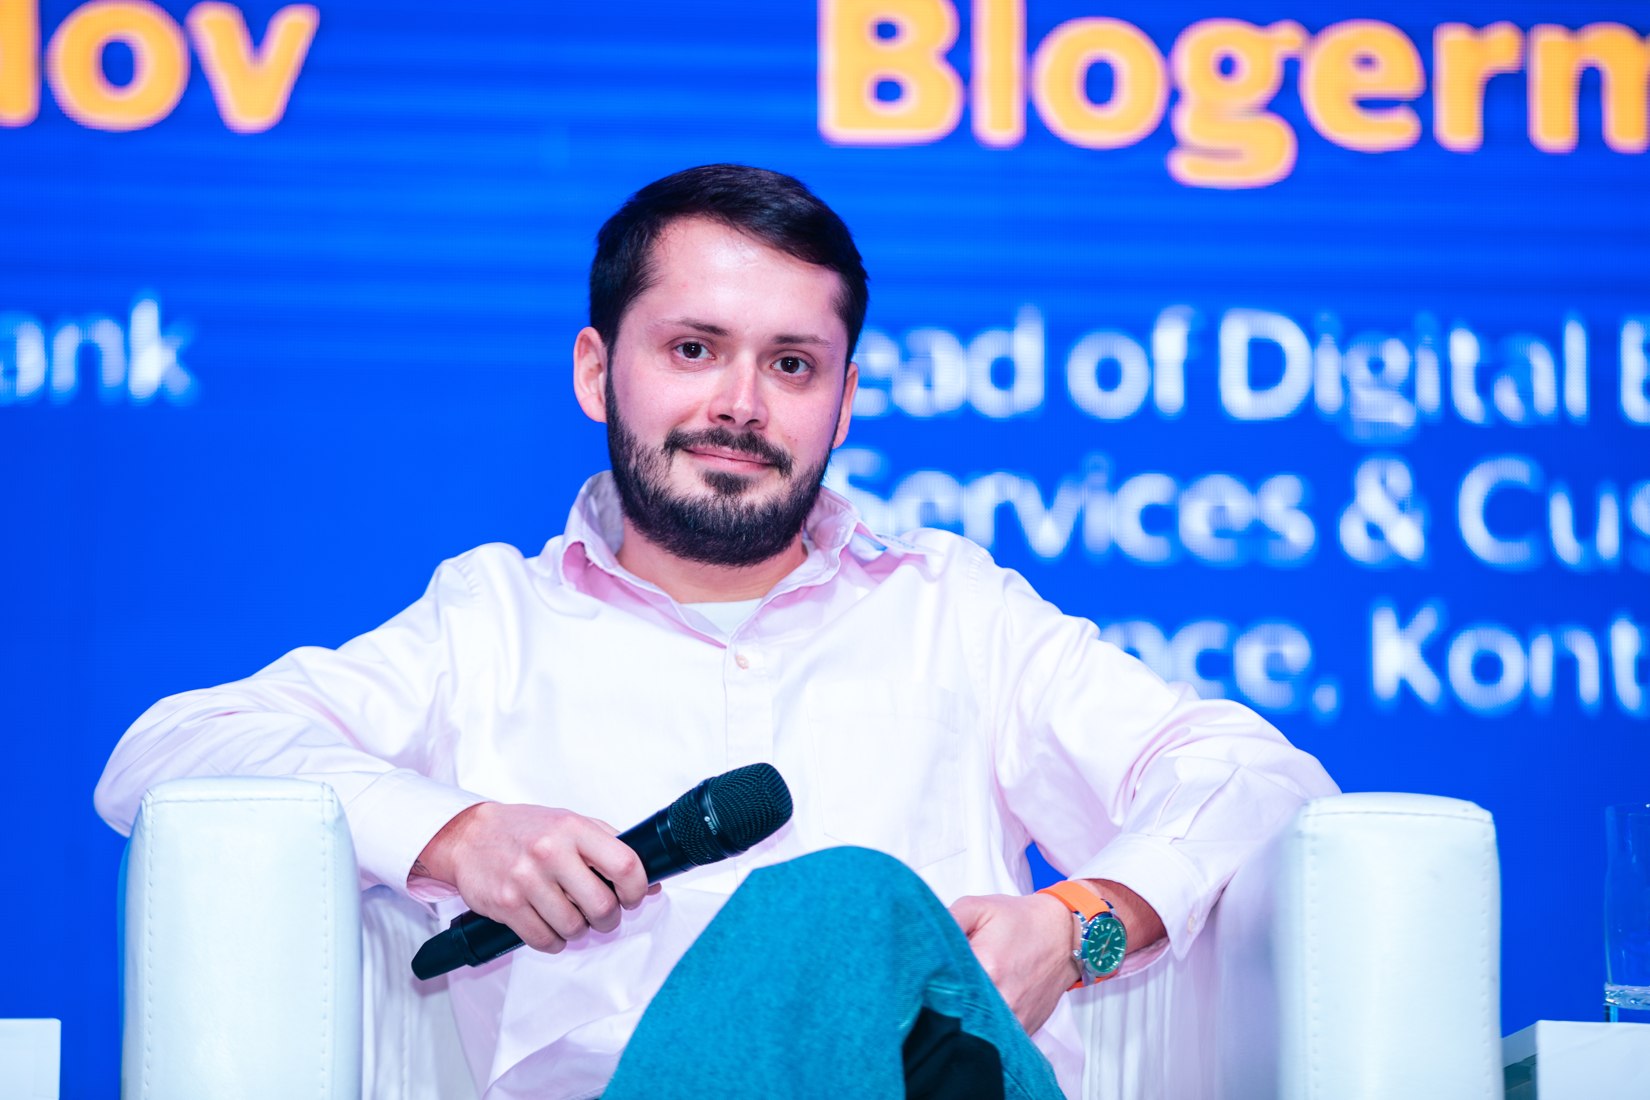
I live in Spain and have worked in four countries.
I’ve spent around ten years running businesses and projects, from manufacturing and retail to digital services.
Tell me what you’re looking to launch, what you already have and where you could use a hand.
© Aleksandr Blogerman